Settlement is Thursday. The roof needs replacing, the roofer cannot get on it until the following week, and neither side wants to move the date. There is a mechanism for exactly this, used regularly at Richmond settlement tables and rarely explained until the week it is needed.
An escrow holdback leaves an agreed sum behind at closing, held by the settlement agent, to pay for work finished after the deed records. The buyer gets the keys, the seller gets paid, and the money waits until the repair is done. Whether you may use it at all is largely your lender’s decision.
- What a holdback is
- When it comes up in Richmond
- Who holds the money
- Why the lender decides
- How one is set up
- Leftover funds and deadlines
- When it is the wrong tool
What an escrow holdback actually is
A written agreement, separate from the purchase contract, under which a stated sum is withheld from the seller’s proceeds and held by a neutral third party until specified work is completed to a specified standard by a specified date. Otherwise the transaction closes normally: title transfers, the loan funds, and the money sits in a trust account rather than the seller’s wire.
It appears on the settlement figures as a deduction from the seller’s side, and the buyer’s Closing Disclosure, the standard form explained by the Consumer Financial Protection Bureau, must reflect it. If it is not in writing and on the settlement statement, it does not exist.
The Richmond situations where it comes up
Holdbacks cluster around work genuinely impossible before settlement rather than inconvenient. Four patterns cover most of it.
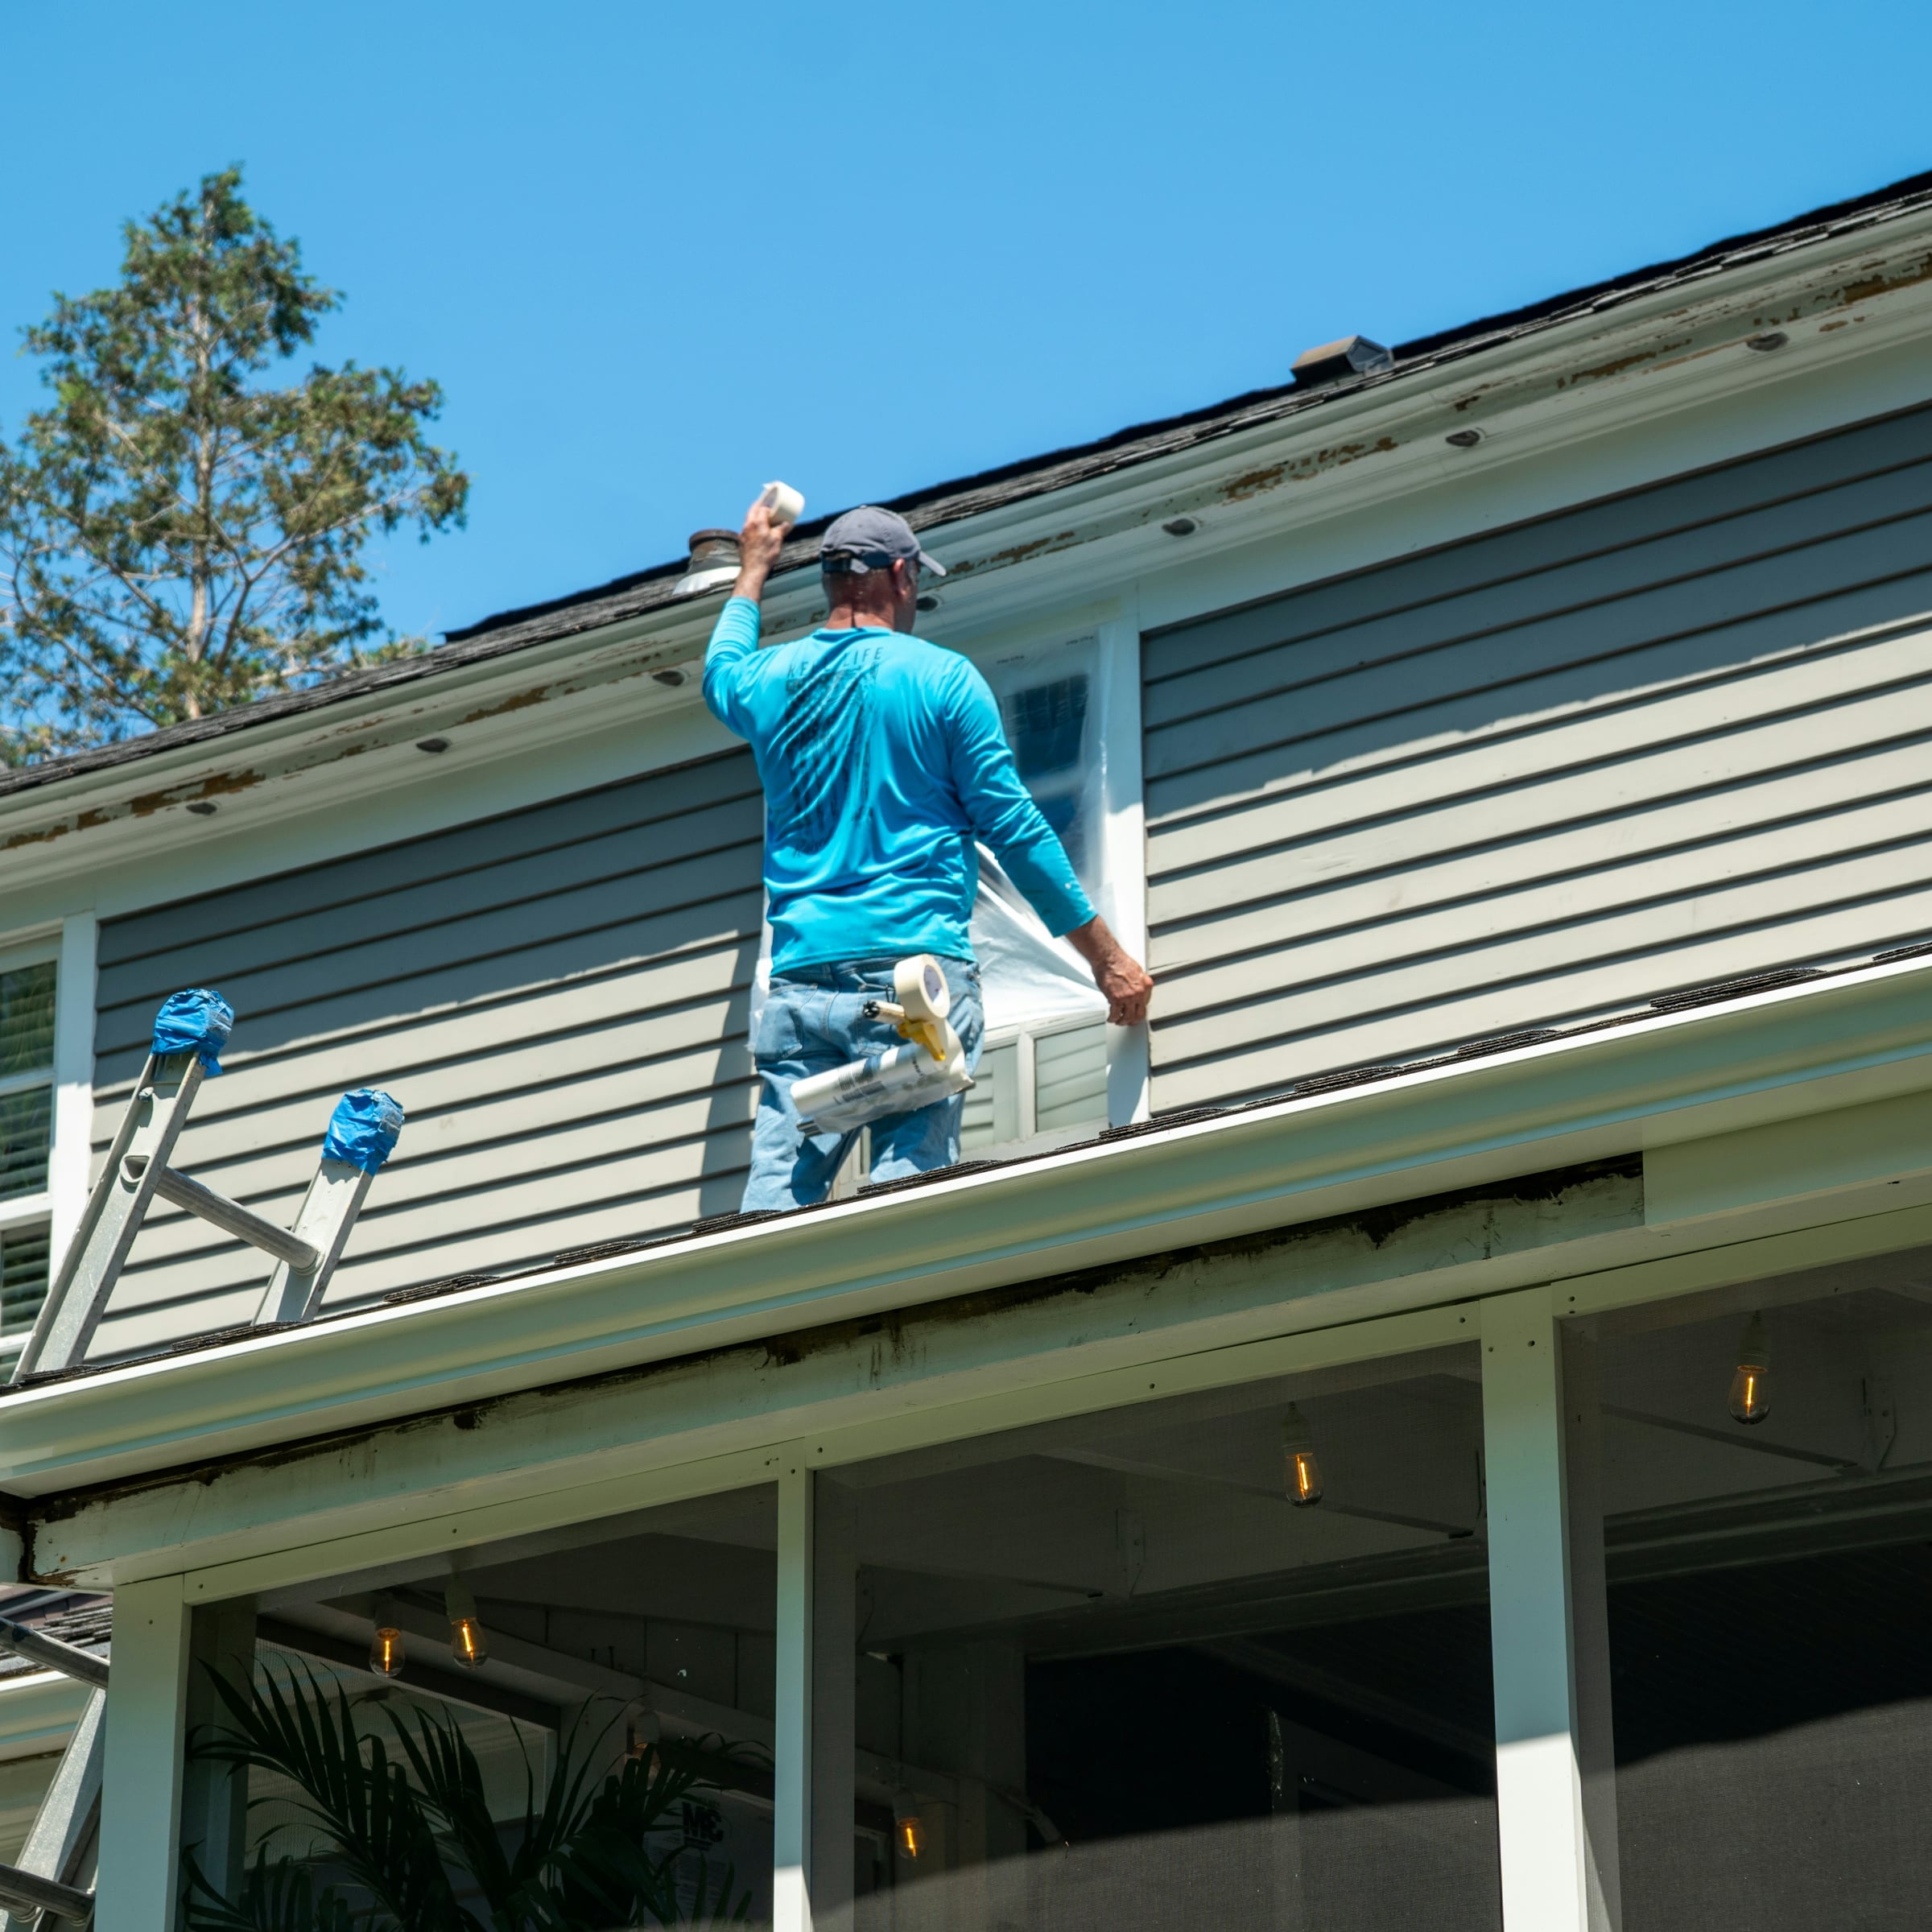
A roof that cannot be replaced in time. The inspection finds a roof at the end of its life, the seller agrees to replace it, and the roofer’s first window is eleven days after settlement. Nobody wants to move the date, because the rate lock and the seller’s onward purchase are tied to it.
Well and septic work. The most common cause in Powhatan County and Goochland County, where much of the stock is on private well and septic. A failed septic inspection, a bacteriological result needing remediation and a retest, or a drainfield repair waiting on a county permit will each outrun a thirty day contract. Most of these properties sit in our Richmond homes with acreage search.
A part on back order. A furnace heat exchanger, an HVAC compressor, an electrical panel component. The contractor is booked and the work priced; the obstacle is a supplier.
Seasonal work. Paving cannot be laid below certain temperatures, and landscaping, grading and exterior painting have weather windows. A January settlement where the seller agreed to repave the driveway is textbook: the work is not delayed, it is impossible for two months.
In each, the problem is timing, not disagreement. Where the parties dispute whether the work is needed or what it costs, a holdback makes the argument worse. That negotiation belongs earlier: see how to negotiate repairs after a Richmond home inspection in 2026.
Who holds the money, and who does not
The settlement agent holds it: in Virginia, the closing attorney or title company conducting the settlement, under a written escrow agreement signed by both parties, holding the funds separately from their own money.
The real estate agents do not hold it. Neither brokerage touches these funds, and an agent offering to “just hold onto it” is describing something that should not happen. Nor does the seller’s attorney, unless that attorney is the settlement agent.
So the escrow agreement, not the purchase contract, is the operative document. Whichever term is missing is what you will argue about.
Why the lender decides, and when they say no
The part that surprises buyers: the lender must approve a holdback, and many will refuse the one you want.
The lender funds a loan against a property in a stated condition, and a holdback admits it is not in that condition on the day the loan closes. So lenders apply their own rules, most commonly that they will not permit a holdback for anything affecting habitability, safety or structural integrity. That rules out an inoperable heating system, an unsafe electrical panel, a failed septic system, an active roof leak, structural movement, and anything the appraiser called out as a condition of value. The repairs most likely to be refused are the ones you most want protection on.
Permitted repair types, maximum amounts and completion windows vary by loan program, investor and lender overlay. [DATA NEEDED: escrow holdback eligibility, maximum amounts and completion deadlines by loan program, from Fannie Mae, Freddie Mac, FHA, VA and USDA primary sources] Ask the loan officer in writing before drafting the repair addendum. Our preferred lenders can usually answer inside a day.
Where the work is substantial, a renovation loan is usually better, because the escrow mechanics are built in. Two to know: the HUD FHA 203(k) rehabilitation mortgage and Fannie Mae HomeStyle Renovation. Have that conversation before contract.
Richmond market context, July 2026
- Richmond Metro, single family: median sold price $460,000 (up 2.2% year over year), 19 average days on market (down 13.6%), 1.8 months of supply (down 5.3%), 1,049 closed sales (up 0.5%)
- Powhatan County, single family, county-level figures: median $486,250 (down 3.4%), 22 days on market (no change), 3.1 months of supply (up 6.9%), 46 closed sales (up 4.5%)
- Goochland County, single family, county-level figures: median $655,000 (down 3.0%), 30 days on market (up 11.1%), 2.8 months of supply (up 3.7%), 44 closed sales (up 51.7%)
- Goochland condominium and townhouse: 1 sale in July 2026, too small a sample to quote a median from.
- [DATA NEEDED: median price per square foot, July 2026, by area]
Month covered: July 2026, the latest published. Source: Central Virginia Regional MLS, July 2026, via the Richmond Association of REALTORS Sortable Statistics.
Powhatan and Goochland run longer market times and more supply than the metro, leaving more room to solve a repair by renegotiating or extending. Where the market is tightest, the pressure to reach for a holdback is highest.
How a holdback is set up, step by step
- Get a written contractor estimate for the specific work. Not a range, not a verbal figure. The escrow amount comes from it and the lender will want to see it.
- Ask the lender whether the item is escrowable on this loan, before anything is agreed with the other side. If the answer is no, everything below is wasted effort.
- Set the amount above the estimate. Commonly one and a half times the estimated cost, leaving room for overruns or a second contractor. Your lender’s required multiple may differ. [DATA NEEDED: required holdback multiple over contractor estimate, by lender and loan program]
- Sign a separate written escrow agreement. It names the escrow agent and amount, describes the work, sets the deadline, states who selects and pays the contractor, defines satisfactory completion and who confirms it, and directs the money in every outcome.
- Decide who selects the contractor, and write it down. Usually the seller, who is paying, with the buyer holding approval rights. Sometimes the buyer manages the work and is reimbursed. Both work; leaving it unstated does not.
- Settle normally. The settlement agent deducts the holdback from the seller’s proceeds, the deed records, the buyer takes possession.
- Complete the work and document it. Paid invoice, any county permit sign-off, photographs. On well and septic work the county or health department record is the one that matters.
- Release the funds. The escrow agent pays the contractor or reimburses whoever paid, on the evidence the agreement specified, and returns the balance as directed.
The arithmetic. A Church Hill rowhouse, roof quoted at $18,000. At one and a half times the estimate the holdback is 1.5 x $18,000 = $27,000, withheld from the seller’s proceeds. The roofer does the work for $18,000 and is paid from escrow. The remaining $9,000 returns to the seller, who was without $27,000 for three weeks and ultimately paid $18,000.
Get the Richmond closing-timeline checklist
A holdback is a deadline problem. It works only if the lender approval, the contractor estimate, the escrow agreement and the settlement date line up, and most that fail started eight days out. Our downloadable Richmond closing-timeline checklist maps every deadline from ratification to settlement.
Request the Richmond closing-timeline checklist and we will send it over.
Leftover funds and the release deadline
Two questions decide whether a holdback ends quietly or in dispute, and only the escrow agreement answers them.
Where does the surplus go? In the Church Hill example $9,000 was left. Most agreements return the balance to the seller, who funded it and whose obligation was to complete the work rather than spend a particular sum. Some split it, a few give it to the buyer. The agreement must say which, because each side will assume it favours them.
What if the deadline passes with the work unfinished? This is the clause people skip and then litigate. A good agreement sets a calendar date and says what happens on it: commonly the buyer completes the work and is reimbursed with the balance to the seller, or the full amount releases to the buyer. That date is set by the parties and their lender, not by any general rule.
A holdback narrows what you inspect for at the walk-through but does not remove the need for one. Our guide to the Virginia final walk-through covers what to check, and the holdback item belongs on that list so its condition is documented.
When a holdback is the wrong tool
Complete the repair before settlement. If possible, do it. Every holdback adds a document, a lender approval, a deadline and a possible argument, none of which exist if the roof is on before the deed records.
Take a price reduction or a closing cost credit instead. Cleaner and faster, and the buyer picks their own contractor. The trade is that the seller loses control over whether the work is done and the buyer carries the overrun risk. We run the arithmetic in seller concessions in Richmond, where the contribution caps also explain why a large credit is sometimes impossible.
Move the settlement date. Less popular than it deserves. If the roofer is eleven days out and the rate lock permits, extending beats escrowing. See what can delay a Richmond closing and how to prevent it.
Get a Virginia attorney on the escrow agreement
An escrow agreement survives settlement, binds money after the deal has ended, and will be read literally if anyone disagrees. It is also usually drafted fast, under pressure.
Have a Virginia real estate attorney review it before signing: the definition of completion and who certifies it, the deadline and what happens on it, the disposition of surplus, whether the seller’s obligation survives an exhausted escrow, and how disputes are resolved. That review costs a rounding error against a five figure holdback.
Our complete guide to Richmond closing costs in 2026 shows how the settlement statement is built and where a holdback sits on it. The CFPB summarises which fees are paid at closing and who pays them.
If an inspection in Midlothian or elsewhere in the region turns up something that will not be fixed in time, our buyer representation page explains how we handle it. The nearest clause to this one is appraisal gap coverage, which moves settlement cash the other way.
Frequently asked questions
Does the buyer or the seller fund the holdback?
The seller, almost always, because the escrow is withheld from the seller’s proceeds. The exception is work the buyer took on at a third party’s requirement, such as an association’s, which can run the other way.
Can we do a holdback on a cash purchase?
Yes, and far more simply, because the hardest approval disappears. With no lender there is nobody to veto the arrangement or impose a multiple, so the terms are whatever the parties and settlement agent put in writing.
Does the holdback earn interest?
Generally these sit in a non-interest-bearing trust account, so assume not. If the sum is large enough that interest matters, raise it while the agreement is being drafted.
What if the repair costs more than the escrow?
This is why the amount is set above the estimate. If it still runs over, the agreement governs, and the question is whether the seller promised to complete the work or only to fund the escrowed sum. Very different promises.
Can I use a holdback for a repair the appraiser required?
Rarely. An appraisal made subject to completion usually requires the work done and re-inspected before the loan closes, the opposite of a holdback. This is among the commonest reasons one is refused.
How long do holdbacks normally run?
Long enough to complete and document the work: weeks for a roof or HVAC part, considerably longer for permitted septic work. There is no standard period and the lender may constrain it. [DATA NEEDED: maximum permitted holdback completion periods by loan program]
Does a holdback affect my title insurance?
The policy issues normally, since title transfers as usual. What it can affect is mechanic’s lien exposure, because work happens after closing. Raise it with the settlement agent and require lien waivers from the contractor on payment.
Can the seller refuse a holdback and give a credit instead?
Yes, and many prefer to, because a credit ends their involvement at settlement. The buyer’s counter is that it gives no assurance the work is ever done. Whether a credit of the size you want is permitted depends on the buyer’s loan contribution cap.
Know your deadlines before the repair problem arrives
Every workable holdback we have seen started early. The same downloadable Richmond closing-timeline checklist maps the inspection period, the repair negotiation window, the lender’s approval path and the settlement date.
Ask us for the Richmond closing-timeline checklist and tell us where you are in your contract. We will mark the dates that apply to your deal.
This is general information about a Richmond settlement practice, not legal advice. An escrow holdback is a binding contract that operates after your closing, and lender rules vary. Have a Virginia real estate attorney review the escrow agreement before you sign it.