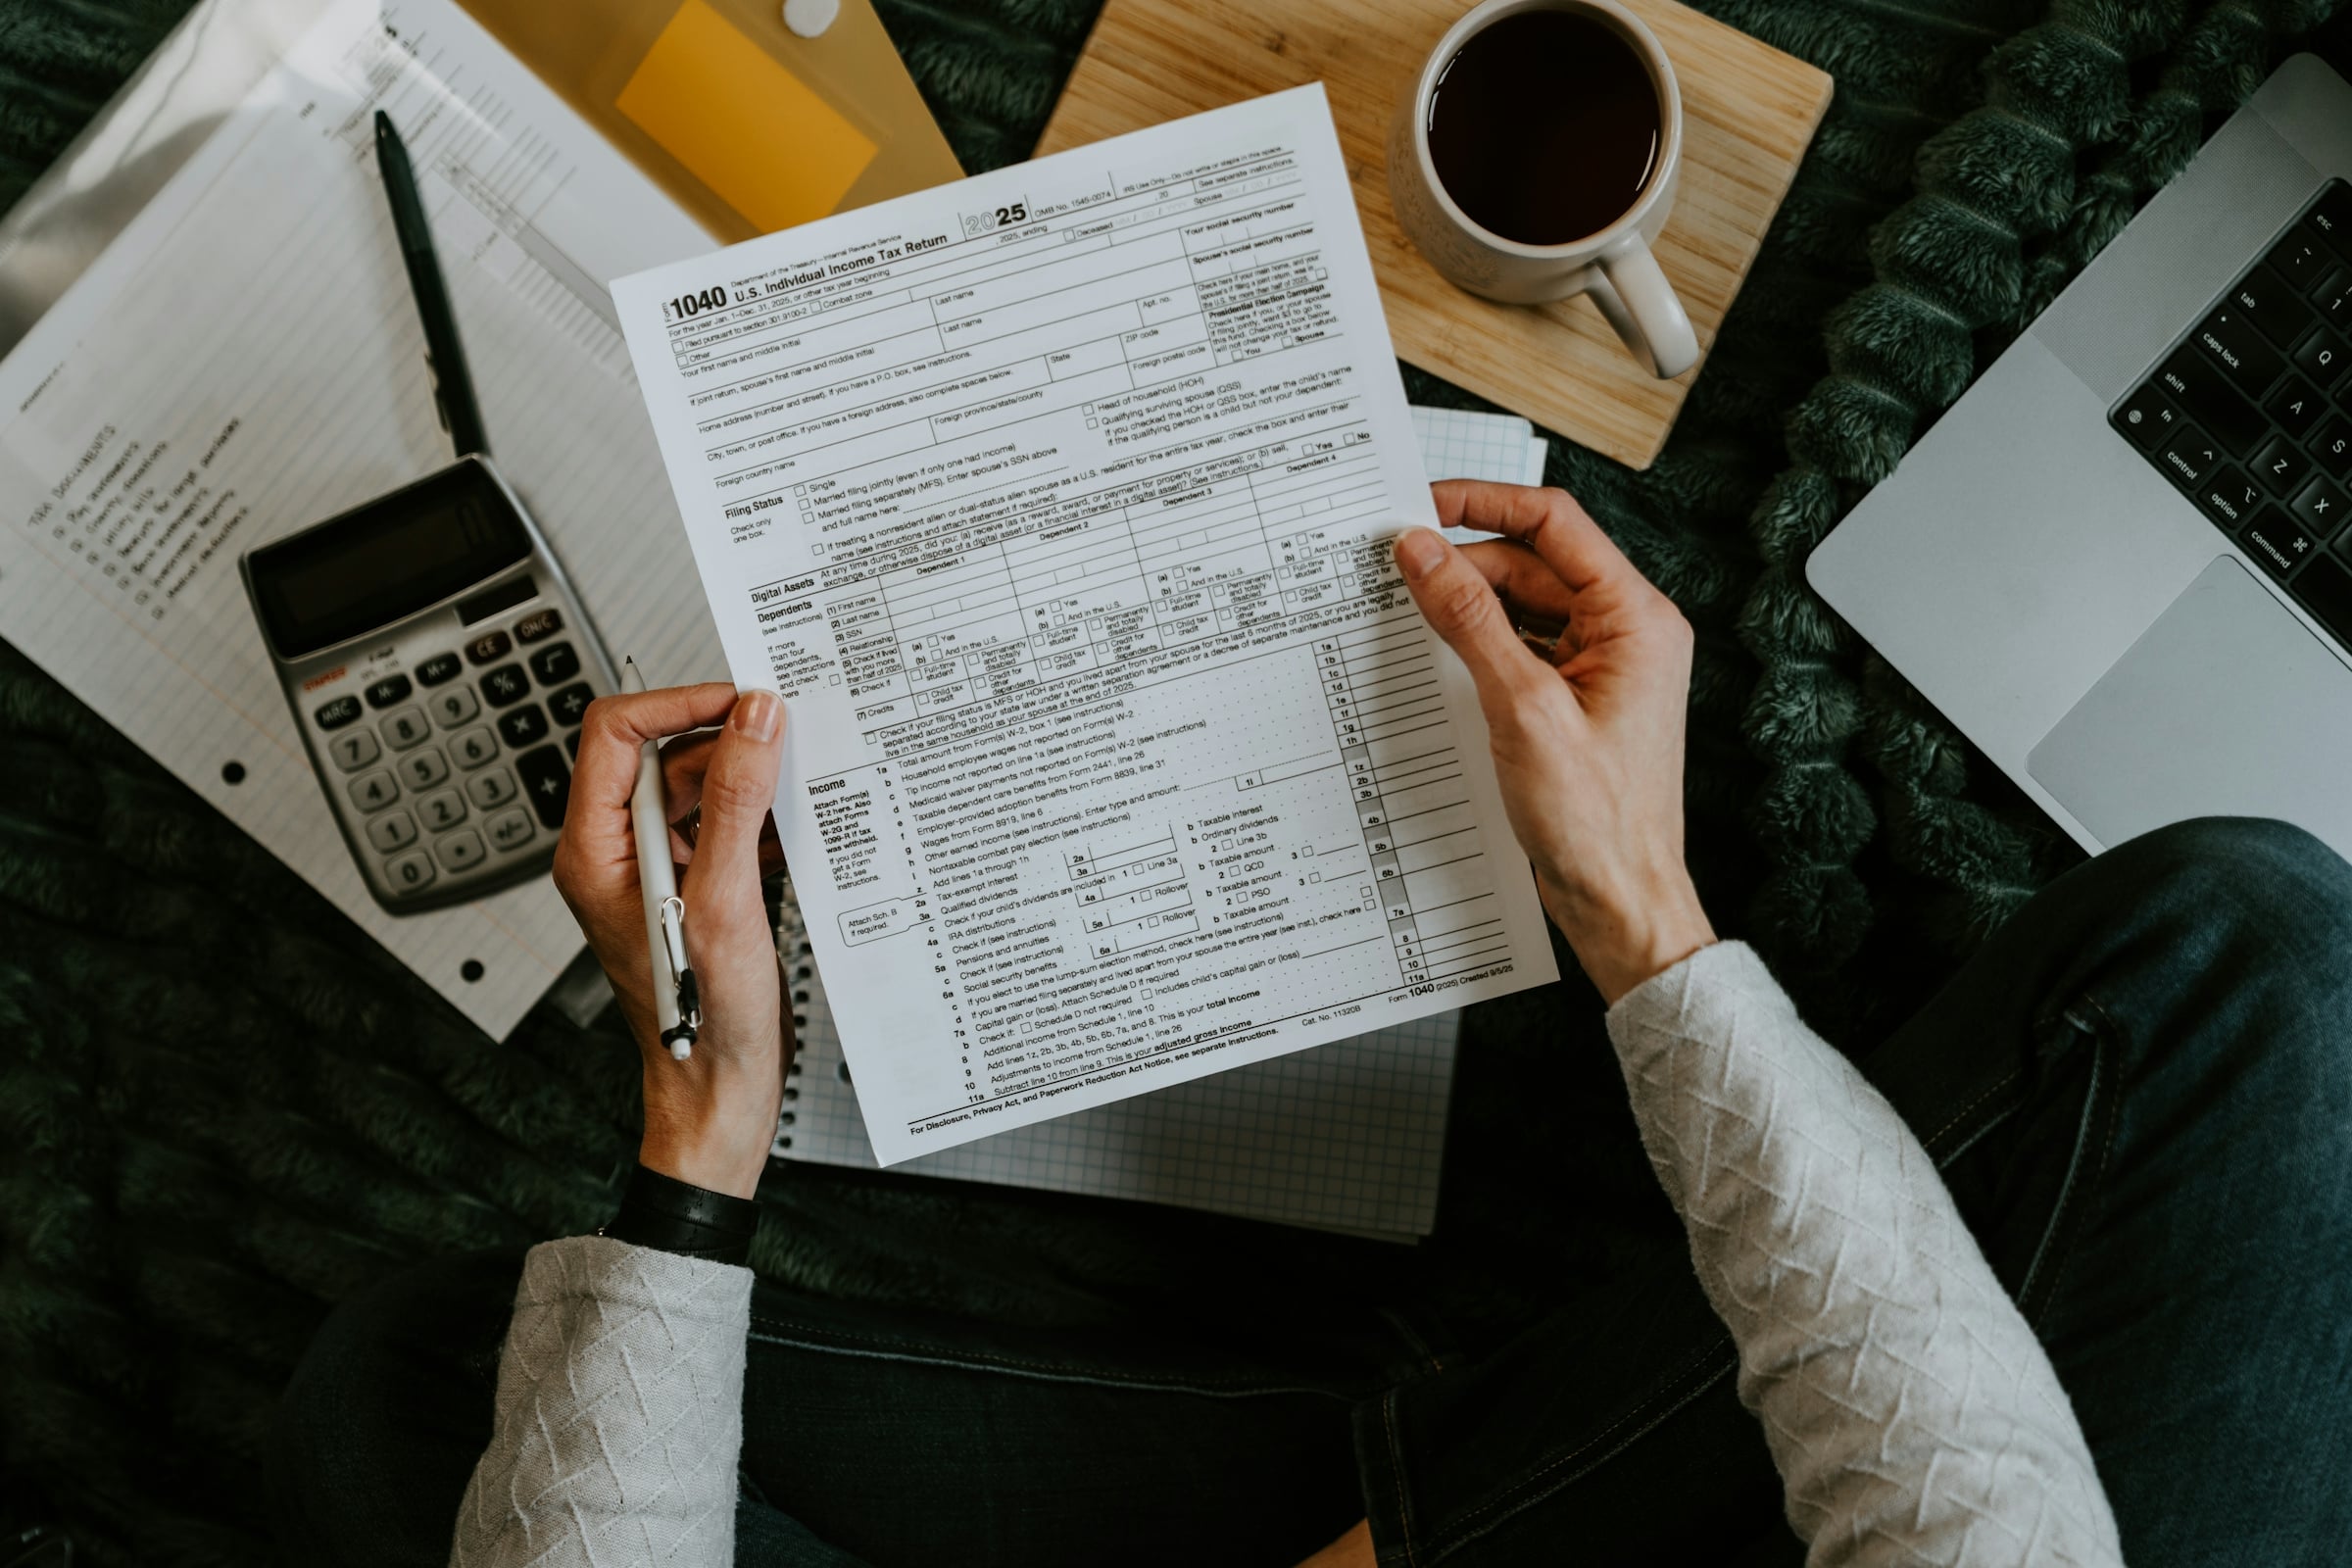
If you are buying a home in the Richmond area today, you should not plan on a Mortgage Credit Certificate from Virginia Housing: its program was suspended as of May 1, 2023, and loans locked after April 28, 2023 are not eligible. If you already hold an MCC, it is still worth real money, and IRS Form 8396 is how you claim it every year, with a few rules around refinancing and selling that can cost you if you miss them.
We checked Virginia Housing’s Mortgage Credit Certificates page and its homeowner resources page on November 5, 2026, along with the IRS page for Form 8396 and the 2025 revision of the form and its instructions. Mission Realty is a brokerage, not a lender or tax adviser. Use this to ask better questions, then talk with a tax professional.
Where the Virginia Housing MCC stands
Virginia Housing’s homebuyer page states in one line that the program is suspended as of May 1, 2023. Its homeowner resources page adds the cutoff for borrowers: loans locked after April 28, 2023 cannot get an MCC, and a homeowner who received one on or before that date keeps it and can use it for the life of the mortgage while living in the home. Virginia Housing’s MCC overview for tax preparers, updated December 2025, repeats that no new MCCs will be issued.
That matters because a lot of older first-time buyer advice still lists the MCC as a Virginia option. If a lender, a relative or an old article mentions it, ask which issuer is offering it now. The IRS rule on Form 8396 is that only a certificate issued by a state or local governmental unit or agency under a qualified program counts, and the home must sit in that issuer’s jurisdiction. Certificates from the FHA, the VA and the former Farmers Home Administration do not qualify.
For new buyers, Virginia Housing’s current loans and down payment help are covered in our guide to Virginia Housing loans for Richmond first-time buyers.
How Form 8396 turns interest into a credit
A credit reduces your federal tax dollar for dollar, which is why the MCC was valuable. Form 8396 works in four steps:
- Interest on the certified amount. Line 1 is the interest you paid during the year on the loan amount shown on your MCC, usually box 1 of your Form 1098. If the MCC covers less than your full loan, you allocate the interest, and IRS Publication 530 shows how.
- Your certificate credit rate. Line 2 is the rate printed on your MCC, not your mortgage interest rate. The IRS says it cannot be less than 10 percent or more than 50 percent.
- The credit. Multiply line 1 by line 2. If your rate is above 20 percent, the credit cannot exceed $2,000 a year, and co-owners other than a spouse split that $2,000 by ownership share.
- The tax limit. The credit cannot exceed your tax, figured on the Credit Limit Worksheet in the instructions. The allowed amount goes on Schedule 3 of Form 1040.
| Form 8396 rule (2025 revision) | Number |
|---|---|
| Allowed range for the certificate credit rate | 10% to 50% |
| Annual cap when the rate is above 20% | $2,000 |
| Years an unused credit can carry forward | 3 tax years |
| Sale window that can trigger recapture | 9 years |
Two catches sit inside those steps. First, if you itemize, you must reduce your Schedule A mortgage interest deduction by the full line 3 credit, even the part you carry forward. Our post on deducting mortgage interest and points explains that deduction, and our SALT cap and mortgage interest post covers whether itemizing pays at all. Second, if your rate is above 20 percent, any credit above the $2,000 cap is lost. It does not carry forward.
Unused credit below the cap carries forward for the next 3 tax years or until used, whichever comes first. The current year’s credit is used first, then the oldest carryforward. Keep each year’s form to figure the next year. You also cannot claim the credit on interest paid to a related person.
No MCC? Ask what you do qualify for
Our lender partners can walk you through the first-time buyer loan and assistance options available on a Richmond-area purchase today, with no guesswork about programs that have closed.
Refinancing can end the credit
The federal rules and Virginia Housing’s guidance point in the same practical direction: be careful before you refinance. The IRS instructions say you can keep the credit after a refinance only if the issuer reissues your MCC and the new certificate meets every condition. It must go to the same holders for the same property, entirely replace the old one, cover no more than the old outstanding balance, carry no higher credit rate and never produce a bigger credit than the original would have. Even with a lower new interest rate, your credit is limited to what the original loan’s scheduled interest would have produced.
Virginia Housing’s tax preparer FAQ states plainly that the credit is no longer valid if the loan is paid off or refinanced. If you hold a Virginia Housing MCC and are thinking about a refinance, ask Virginia Housing directly whether any reissue is possible before you lock, and have a tax professional compare the credit you would give up with what the new loan saves. The same caution applies if you are considering paying off your mortgage early, since a payoff also ends the loan the certificate covers.
Selling within nine years: the recapture test
The Form 8396 instructions warn that if you bought with an MCC and sell within 9 years, you may owe some of the benefit back. That is figured on Form 8828, Recapture of Federal Mortgage Subsidy. Reading the November 2024 revision of the form, three limits protect many sellers:
- If you sell at a loss, there is no recapture tax.
- The tax can never exceed 50 percent of your gain on the sale.
- If your modified adjusted gross income in the year of sale is not above the adjusted qualifying income figure in the instructions, you owe nothing. Between zero and $5,000 over that figure, only a percentage applies.
The form also applies a holding period percentage, which depends on how long you owned the home. Virginia Housing’s homeowner page links a short explainer on the recapture tax. If you are thinking about selling an MCC home, ask a tax professional to run Form 8828 with you before you list. Our selling page covers how we plan a sale, and the tax question belongs on that list early.
If you are buying from someone who has an MCC
An MCC is tied to the holder’s loan and main home, not to the property. Virginia Housing’s tax preparer FAQ says the credit ends when the property is sold or stops being the borrower’s primary residence. A buyer does not inherit it, and a seller cannot offer it as a feature of the house. The same applies if the holder moves out and rents the home.
What to claim if you hold an MCC today
Virginia Housing’s tax preparer FAQ lists what goes on the return: the total interest paid for the year from your lender’s Form 1098, plus the MCC issuer, certificate number, issue date and credit rate from the certificate itself. The FAQ says the MCC was mailed about a month after closing. If you have lost yours, Virginia Housing’s FAQ explains how to request a copy, and it says a fee may apply.
What new buyers can use instead
Without an MCC, the federal tax side of buying comes down mostly to the mortgage interest and property tax deductions, and only if you itemize. On the Virginia side, the state’s first-time home buyer savings account subtraction lets savings earnings for a first home come out of Virginia taxable income. Neither is a substitute for picking a payment you can carry, so start with the mortgage calculator and a lender conversation.
Then look at what is for sale in the places you are weighing, from the City of Richmond to Henrico County, Chesterfield County and Hanover County, on our Richmond-area property search.
Get a first-time buyer plan from a lender partner
Ask one of our preferred lenders which programs fit your income and price range now that the Virginia Housing MCC is closed to new loans.
Mortgage interest credit questions
Can I still apply for a Virginia Housing MCC at closing?
No. Virginia Housing’s homebuyer page says the program was suspended as of May 1, 2023, and its homeowner page says loans locked after April 28, 2023 are not eligible. Its tax preparer FAQ also notes that MCC applications cannot be processed after a loan closes.
Is the mortgage interest credit refundable?
No. Form 8396 limits the credit to your tax liability using the Credit Limit Worksheet in the instructions. Any unused amount within the rules carries forward for up to 3 years instead of coming back as a refund.
Do I need to itemize to claim the credit?
No. The credit goes on Schedule 3 of Form 1040 whether or not you itemize. Itemizing only changes one thing: you must reduce your Schedule A mortgage interest deduction by the credit amount on line 3.
My spouse and I bought together. Do we each get $2,000?
No. The $2,000 cap for rates above 20 percent is per certificate. The instructions say it is allocated by ownership share only among owners other than a spouse filing jointly, so a married couple filing jointly claims one credit.
Does the credit stop if I rent the house out?
Yes. Virginia Housing’s tax preparer FAQ says the credit is no longer valid if the property stops being the borrower’s primary residence, and Form 8396 requires the home to be your main home.
Where do I find my certificate credit rate?
It is printed on the MCC itself. Form 8396 warns not to enter your mortgage interest rate on line 2. If you cannot find the certificate, Virginia Housing’s tax preparer FAQ explains how to request a reprint.
Is recapture the same as paying back every credit I claimed?
No. Form 8828 figures recapture from a federally subsidized amount, a holding period percentage and an income percentage, then caps it at 50 percent of your gain. Sell at a loss and the tax is zero.